New Mexico Dump Truck and Aggregate Hauler Insurance
8:30am - 5:00pm Mon-Fri
Will Reply in 15min*
Over 180+ commercial clients covered
100% customer satisfaction guaranteed
Over 10 years of business insurance experience
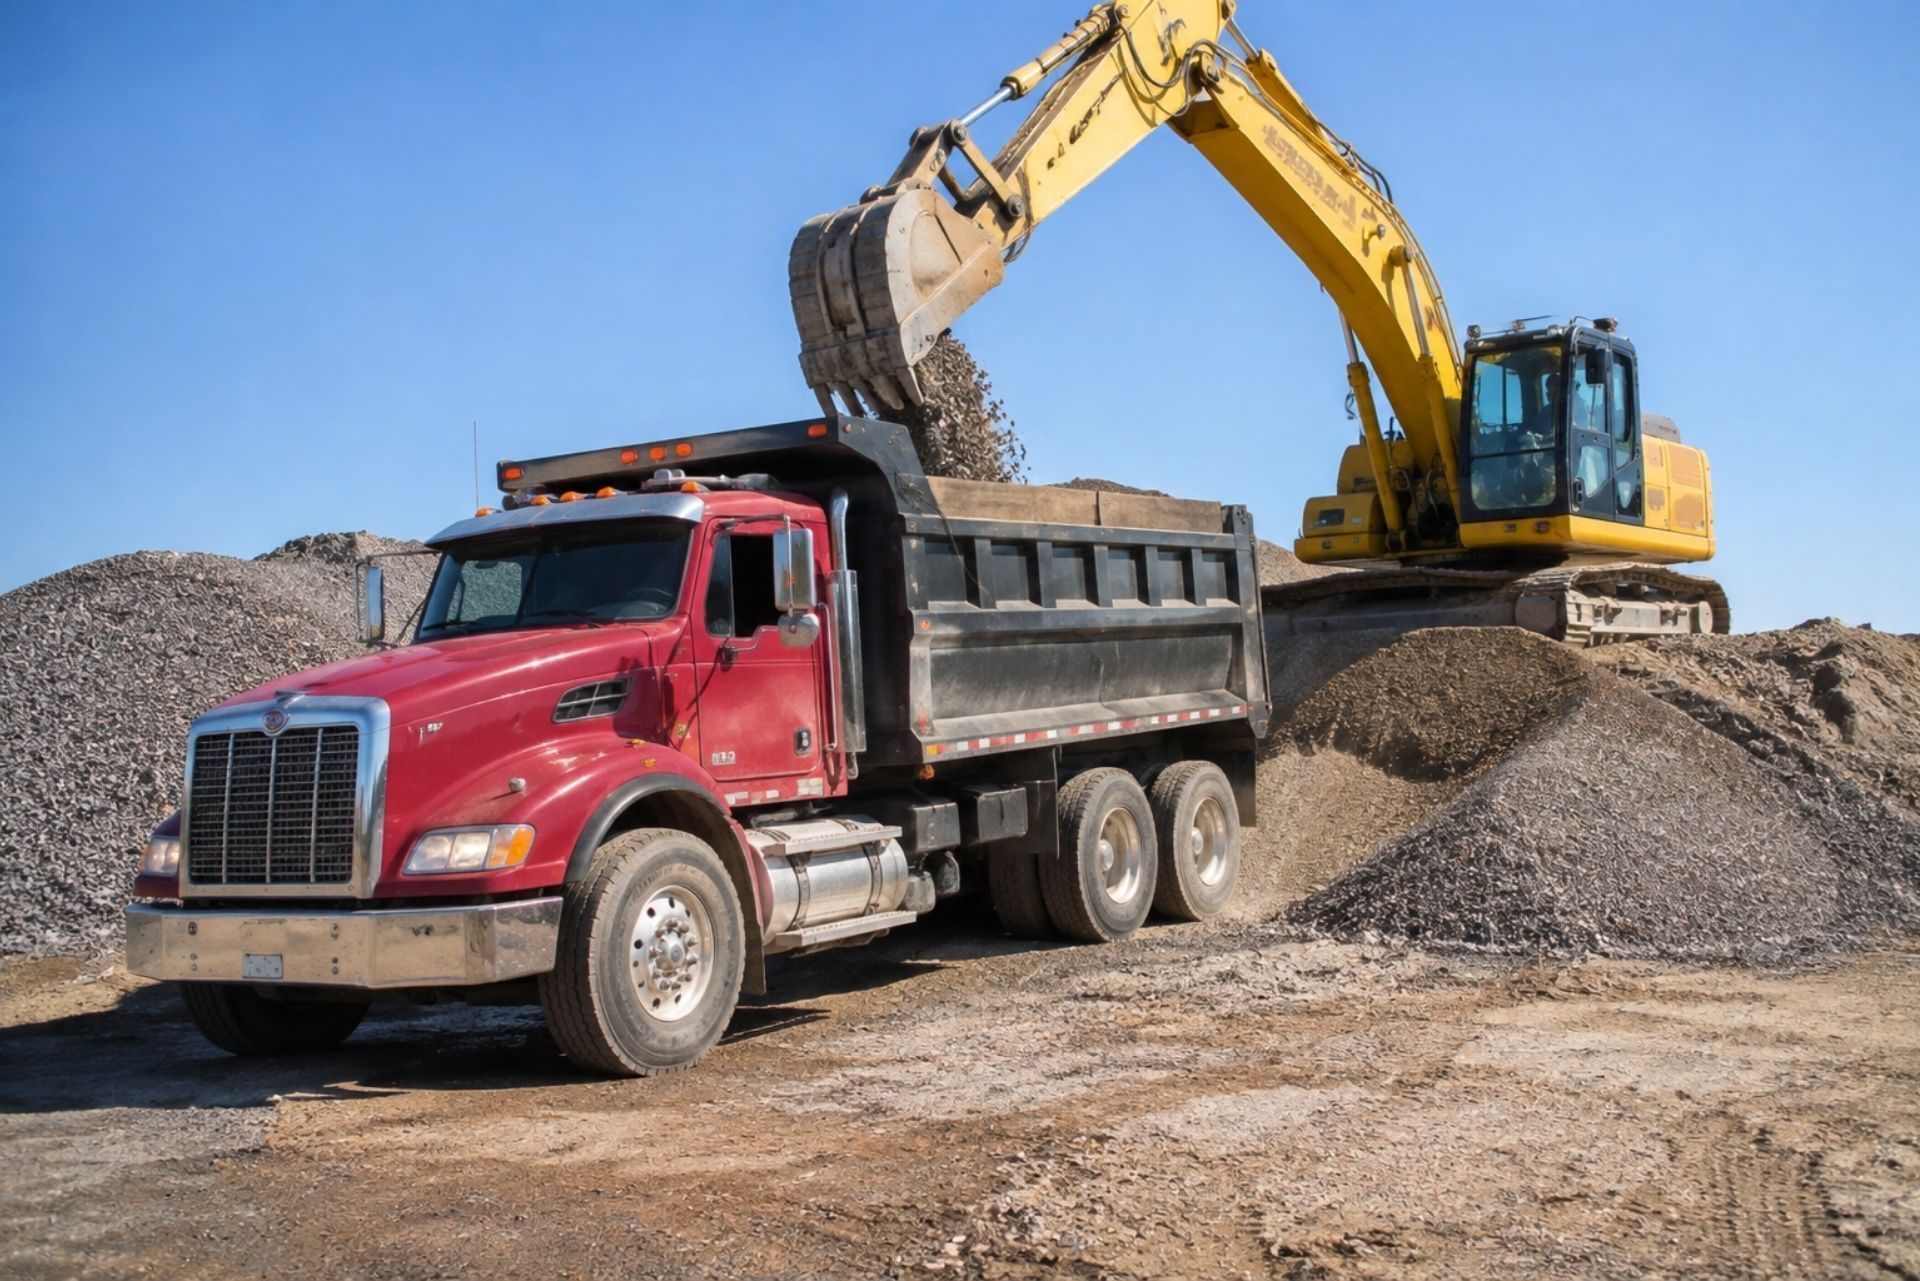
Hauling base course from a Belen pit to a highway job near Socorro doesn't look like a high-risk day on paper. Then a tarp strap snaps at 65 mph, a rock stars a windshield behind you, and two weeks later you're reading a demand letter. Insurance for New Mexico dump truck and aggregate haulers exists to handle that kind of day, along with the rollover, the injured driver, and the dropped load of asphalt that cooled before it reached the paver.
This guide covers the policies New Mexico sand, gravel, and asphalt haulers carry and where coverage gaps tend to show up. It also explains what moves your premium up or down. We'll walk through state minimums, workers' comp rules, cost ranges, and the 2026 regulatory changes that hit heavy trucks hard.
If you run one truck or twenty, the goal is the same: buy the protection your contracts and risk demand, and stop paying for coverage that doesn't fit how you operate.
New Mexico is a tough state to insure heavy trucks in. You've got long rural stretches, oilfield traffic in the Permian Basin, monsoon-season washouts, and a construction market that swings with state and federal road funding. Underwriters price all of that into your policy.
The regulatory side shifted in 2026, too. Effective July 1, 2026, New Mexico rolled out a 35% increase in Weight Distance Tax rates for vehicles over 26,000 lbs. That's not an insurance premium, but it lands on the same balance sheet. For a hauler running tandem or tri-axle dumps, it tightens margins at the same time insurance renewals are coming due.
Compliance paperwork matters here as well. Carriers need an annual Electronic WDT Permit for each vehicle and must file quarterly returns, due the last day of the month after each quarter ends. Fall behind, and you can face permit problems that ripple into your ability to work state jobs.
Here's what that means for your insurance planning:
- Contracts drive limits. NMDOT projects and large general contractors often require limits well above state minimums.
- Personal policies won't respond. A personal auto policy excludes vehicles used to haul materials for hire, even a pickup towing a small dump trailer.
- Operation type changes everything. Intrastate for-hire, private carriage for your own excavation work, and interstate hauling each carry different filing and coverage needs.
Getting the classification right at the start prevents most of the claim denials we see.
By: Dax Kastrin
Founder and Agent at ERM Insurance
Core Liability Coverages for Aggregate Haulers
Liability is where the big losses live. A physical damage claim tops out at the value of your truck. A liability claim can run past your policy limits and reach your business assets.
Primary Auto Liability and State Minimums
Primary auto liability pays for bodily injury and property damage you cause to others while operating your truck. For New Mexico intrastate for-hire property carriers, the rule is specific: you must maintain at least $750,000 in combined single limit liability for vehicles over 10,000 lbs.
The catch is that $750,000 rarely satisfies a real contract. Most general contractors and public agencies ask for a $1,000,000 CSL, and some larger projects want an umbrella stacked on top. Picture a loaded dump truck rear-ending a minivan on I-25 near Las Cruces with three injured passengers. Medical bills, lost wages, and vehicle damage can blow past $750,000 before attorneys get involved.
Watch for these nuances:
- Scheduled autos vs. any auto. If your policy only covers listed trucks, a newly purchased truck may have no coverage until you add it.
- Hired and non-owned auto. This covers you when an employee runs a parts errand in a personal vehicle or you rent a truck during a breakdown.
- Spilled load liability. Rocks falling from your bed and damaging cars behind you typically fall under auto liability, so confirm there's no restrictive endorsement.
That last point matters more than haulers think. Unsecured debris causes an estimated $10 million in annual cleanup costs on New Mexico roads, and state law requires loads to be secured. A windshield claim from flying gravel is one of the most frequent losses in this class.
General Liability for Off-Road Job Sites
Auto liability covers the truck while it's being used as a vehicle. General liability covers your business operations outside that use, and job sites blur the line constantly.
Say your driver dumps fill at a residential site and the load rolls into a neighbor's fence. Or you spread gravel on a driveway and a client trips over the edge you left. Depending on the policy wording, those can land under GL rather than auto. Many haulers skip GL because they think "I just drive," and then discover the auto carrier denied a claim that happened after the truck was parked.
A standard GL policy for haulers often carries $1M per occurrence and $2M aggregate. It also responds to completed operations claims, like a driveway base that fails because of how it was spread and compacted. If you do any spreading, grading, or site work, tell your agent, because those operations change your classification and price.
Protecting Your Assets: Physical Damage and Cargo
A used tandem dump truck can represent a six-figure investment, and lenders won't finance one without physical damage coverage. The load you carry is a separate exposure that a lot of haulers ignore.
Collision and Comprehensive Coverage for Heavy Equipment
Collision pays to repair or replace your truck after an accident, regardless of fault. Comprehensive covers non-collision losses: theft, fire, vandalism, hail, and that monsoon flash flood that swamps your yard in Roswell.
The single biggest mistake we see is a stated value that's out of date. You bought the truck for $140,000 three years ago, never updated the policy, and the insurer pays based on the lower figure or applies depreciation you didn't expect. Review values every renewal.
Ask about these items specifically:
- Dump body and hydraulics. Confirm the box, hoist, and tarp system are included in the stated value.
- Rollover exposure. Dumping on uneven ground causes tip-overs, which are collision claims and can total a truck.
- Rental reimbursement. Downtime during repairs costs you loads, and some policies add a daily allowance for a replacement unit.
- Deductible choice. Raising from $1,000 to $2,500 lowers premium, but only if you can cash-flow that hit.
Motor Truck Cargo for Sand, Gravel, and Asphalt
Motor truck cargo pays for damage to the freight you haul. For sand and gravel, the load value per trip is low, so many haulers skip it. That's usually fine for pit run. It's a different story with hot mix asphalt, specialty aggregate, or frac sand.
Consider a breakdown on US-285 with a load of hot mix. By the time a tow arrives, the asphalt has set up in the bed. Now you've got a lost load and a bed full of hardened material that needs chipping out. Some cargo forms exclude temperature-related losses, so read the exclusions closely.
Contracts in the oilfield often require cargo coverage regardless of material value. Cargo policies also tend to exclude unattended vehicles and certain commodities, so make sure your scheduled commodities match what you actually haul.
Workers' Compensation Requirements in New Mexico
Workers' comp is the policy owner-operators most often get wrong, either by assuming they're exempt or by misclassifying drivers as independent contractors. The New Mexico Workers' Compensation Administration oversees the system, and construction-related employers face stricter coverage thresholds than many other businesses. Hauling aggregate to job sites can pull you into that category, so confirm your obligation with the WCA or your agent rather than guessing.
Benefits tie to wages. The WCA set the State Average Weekly Wage at $1,146.66 effective January 1, 2026, which drives the maximum weekly benefit for injured workers. As that figure climbs, so does the potential cost of a lost-time claim.
Injuries in this trade are specific and repetitive. Drivers fall climbing onto the bed to pull a tarp. Fingers get caught in tailgate latches. A driver strains a back shoveling out a stuck load of wet sand. Any of those can mean months of wage replacement and medical care.
The contractor question deserves attention. If you hire a driver, set his schedule, and he drives your truck, calling him a 1099 contractor won't hold up after an injury. Your insurer may charge premium for him at audit anyway, and if you have no policy, you're personally exposed to the claim.
Speaking of audits: workers' comp premium is based on estimated payroll. If you estimate $150,000 and actually run $240,000 because you added drivers mid-season, expect an additional bill at year-end. Update your carrier when payroll changes so that bill doesn't surprise you.
Comparison: Basic vs. Comprehensive Insurance Packages
Not every hauler needs every coverage. A one-truck operator hauling pit run for local landscapers has a different profile than a fleet running asphalt for NMDOT contracts. Here's how the two approaches stack up.
| Coverage | Basic Package | Comprehensive Package |
|---|---|---|
| Auto Liability | $750,000 CSL (state minimum for intrastate for-hire) | $1M CSL plus umbrella |
| General Liability | Often skipped | $1M/$2M with completed ops |
| Physical Damage | Liability only or high deductible | Collision and comp, updated values |
| Motor Truck Cargo | None | Scheduled to actual commodities |
| Workers' Comp | Only if legally required | Full payroll covered, accurate audit |
| Rental Reimbursement | None | Included |
| Best For | Paid-off truck, local residential work | Financed fleet, contract and DOT work |
| Main Risk | Contract rejection, uncovered losses | Higher upfront premium |
The basic package keeps cash in your pocket today but locks you out of bigger jobs. General contractors won't issue a subcontract if your certificate of insurance shows $750,000 when they require $1M. You'll also absorb any job-site claim that falls outside your auto policy.
The comprehensive approach costs more, but it opens doors. Fast COI turnaround matters here too, because a GC who waits three days for your certificate may give the load to someone else.
Factors Influencing Insurance Costs in the Southwest
Pricing in this class varies widely. Established local haulers in sand and gravel often pay roughly $400 to $1,200 per truck per month. Annual premiums for a standard semi-dump in New Mexico generally fall between $9,000 and $16,500, and specialized sand haulers working high-risk areas like Hobbs or Carlsbad frequently pay upwards of $16,000.
Why the spread? Underwriters look at how much risk each unit carries, and a few factors dominate.
The Impact of Driving Records and CDL Experience
Drivers are the biggest rating factor. Insurers pull motor vehicle records on every listed driver, and a single at-fault accident or speeding ticket in a commercial vehicle can raise rates or get a driver excluded.
Experience thresholds matter. Many carriers want drivers with at least a couple years of verifiable CDL experience, and newer drivers can push you into nonstandard markets with higher prices. A hauler who hires a 22-year-old fresh out of CDL school might find that one driver adds thousands to the annual premium. Before you hire, ask your agent to run the driver's MVR against your carrier's guidelines.
Equipment Age and Operational Radius
Older trucks cost less to cover on physical damage because their values are lower. The trade-off: underwriters may worry about brake condition and maintenance, especially on units without documented service records.
Radius plays a large role. A truck staying within 50 miles of an Albuquerque yard faces less exposure than one running daily to the Permian Basin. Oilfield routes around Hobbs and Carlsbad carry heavy traffic, fatigue risk, and rough roads, which explains the higher premiums there. Be accurate about radius on your application. Understating it can lead to a denied claim if an accident happens outside the declared area.
You can't control the market, but you control a lot of what underwriters see. These steps tend to produce real savings:
- Hire carefully. Set a minimum CDL experience standard and check MVRs before making offers, not after.
- Install telematics and dash cams. Forward-facing cameras help defend against fraudulent claims, like the driver who brake-checks your truck on purpose. Some carriers offer credits for them.
- Write a load-securement policy. Train drivers on tarping and document it. Fewer windshield claims means better loss runs.
- Pay annually if you can. Installment plans often add fees.
- Raise deductibles strategically. Do it on physical damage first, where claim frequency is lower.
- Keep payroll and revenue estimates accurate. That prevents audit shocks and the cash crunch that follows.
- Shop at renewal, not mid-term. Start 60 to 90 days out so you can compare quotes line by line.
When comparing quotes, don't stop at price. Check whether each quote includes the same limits, GL completed operations, hired and non-owned auto, and cargo exclusions. A cheaper quote missing spilled-load coverage isn't cheaper after your first windshield claim.
Clean loss runs are your strongest asset. Three years without at-fault accidents puts you in front of preferred carriers that won't even quote a fleet with recent losses. Treat safety as a premium-reduction tool, because underwriters do.
Common Questions About New Mexico Trucking Insurance
What's the minimum auto liability for a dump truck in New Mexico? Intrastate for-hire property carriers with vehicles over 10,000 lbs need at least $750,000 combined single limit. Most contracts require $1M or more.
How much does dump truck insurance cost in New Mexico? Established local haulers often pay $400 to $1,200 per truck monthly. Semi-dumps commonly run $9,000 to $16,500 a year, with oilfield-area haulers paying more.
Can I use my personal auto policy on a small dump truck? No. Personal policies exclude business use and hauling for hire, so a claim would likely be denied.
Do I need workers' comp if I'm an owner-operator with no employees? Usually not for yourself, though some contracts require proof of coverage. Once you hire drivers, check your obligation with the Workers' Compensation Administration.
Does the Weight Distance Tax increase affect my insurance? Not directly. It raises your operating costs, so budget for both together at renewal.
Is cargo insurance worth it for gravel loads? For low-value pit run, often not. For hot mix asphalt, frac sand, or contracts that require it, yes.
Making the Right Choice for Your Fleet
Picking the right coverage for your dump trucks comes down to matching policies to how you actually work. A local residential hauler and an oilfield sand operator shouldn't buy the same package, and neither should settle for the bare $750,000 minimum if they want contract work.
Start with accurate information: real driver records, true operating radius, current truck values, and honest payroll estimates. Build from there with auto liability sized to your contracts, GL for job-site exposure, physical damage on financed units, cargo where the material or contract demands it, and workers' comp the moment you add drivers.
With the 2026 Weight Distance Tax increase squeezing margins, every dollar counts. Review your policy every year, shop renewals early, and treat your safety program as part of your insurance strategy. The haulers who control their loss history are the ones who control their premiums.
About The Author:
Dax Kastrin
As Founder and Agent at ERM Insurance, I’m committed to helping clients understand and manage risk through clear, straightforward coverage solutions. With professional designations as an Accredited Advisor in Insurance (AAI) and Associate in General Insurance (AINS), I focus on delivering dependable protection and personalized service for every individual and business I work with.
Your Business Insurance Solutions
Workers’ Compensation Insurance
Protect your workers from significant financial losses if they are injured or disabled while performing their duties as an employee.
Cyber Liability Insurance
Safeguard your business against financial losses from data breaches, especially those that involve sensitive customer information and other unforeseen cyber events, like cybercrime.
Directors & Officers Liability
Protect your C-suite officers and board members, as well as the companies they represent if they are the subject of a claim or investigation from their duties.
General Liability Insurance
Guard your business against the cost of claims that can be filed due to bodily injury to a third party, damage to third-party property, lawsuits, and more.
Business Owners Insurance
Reduce the cost of premiums by getting a business owner’s insurance, a coverage plan that combines commercial property insurance and general liability insurance.
Commercial Auto Insurance
Guard your business against financial losses from accidents involving company vehicles. Commercial auto insurance provides for bodily injury liability and property damage.
Commercial Property Insurance
Recover from financial losses involving damage to your physical assets, including furniture, physical building, office space, inventory, landscaping and fencing, signage, and more.
Lessor's Risk Insurance
Get coverage for your rental properties. A lessor’s risk insurance covers financial losses from acts of vandalism, litigation costs for lawsuits, theft of property owned by your tenants, and more.
Product Liability Insurance
Protect your companies from claims made against the goods you provide. This covers injuries caused by malfunctions of products, design defects, and more.
Choose Elemental Risk Management Today
Get a Plan Suited to Your Business
ERM assesses the risks that your company faces, as well as your industry, operations, workforce, and more.
Recover Quickly
With business insurance coverage, you’ll bounce back from adverse events that could have left your business on the brink of bankruptcy.
Avoid Overpaying
Through customized solutions, your business will get adequate coverage without unnecessary costs. We’ll keep premiums cost-effective.
Our Testimonials
Hear from our clients
“We recently changed our business insurance after over 20 years, and we couldn't be happier. We didn't realize how poor the service was, how unresponsive, and slow the service was of our previous carrier. Dax and his team have gone above and beyond to answer every question our business had, to ensure that we had the coverage we needed, and fully understood everything we were getting. Not only did we save money, but we have saved a lot of time with the quick responsiveness of this team. They are exceptional. Would Highly recommend, and provide references."
Laura Harrison
May 2021
"I love working with the ERM crew! They are always super inquisitive and willing to learn/ask questions to provide their clients with the best possible insurance solution. I would definitely recommend them to anyone looking for advice on their current policies and coverage."
Nicole Limpert
May 2021
“Elemental Risk Management has been our insurance agent for 2 years now. They are consistently shopping for us to have the very best quality of coverage, as well as the best rates available. They saved our company over $20,000.00 in premiums our first year doing business with them. They are also quick to respond to any need (COI's, accident reporting, etc.). I recommend the team at ERM very highly!
Ramona Mills
June 2021