California Solar Farm Insurance
8:30am - 5:00pm Mon-Fri
Will Reply in 15min*
Over 180+ commercial clients covered
100% customer satisfaction guaranteed
Over 10 years of business insurance experience
California's solar industry generates enormous value, but it also sits squarely in the path of wildfires, earthquakes, and grid volatility. If you own or operate a solar farm here, the insurance conversation isn't optional: it's foundational. A single wildfire season can wipe out years of revenue, and a moderate seismic event can twist racking systems beyond repair. Understanding the full spectrum of coverage, from property and liability to business interruption and equipment breakdown, is what separates a protected investment from an exposed one. The insurance market itself is shifting fast. Assets exposed to catastrophic risk now face
stricter underwriting and mandatory mitigation requirements, even as traditional property rates begin to soften for well-managed portfolios. That means your location, your equipment choices, and your risk management strategy all directly affect what you'll pay and what you can actually get covered. This guide walks through the essential coverages for solar farm insurance in California, the state-specific hazards that shape your policy, and the practical decisions that influence your premiums.
Core Insurance Coverages for California Solar Farms
Every solar farm policy starts with a handful of core coverages. These aren't luxuries or add-ons. They're the structural foundation that keeps your project financially viable after a loss event. The specifics vary by insurer, but the categories below apply to virtually every California solar installation, whether it's a 5 MW community project or a 200 MW utility-scale plant.
Physical Damage and Property Insurance
Property insurance covers the physical assets themselves: panels, inverters, transformers, substations, and the structures supporting them. In California, this coverage gets complicated because standard policies often exclude wildfire and earthquake damage, requiring separate endorsements or standalone policies. You'll want replacement cost coverage rather than actual cash value, since solar equipment depreciates quickly on paper but costs just as much to replace. Pay attention to sublimits on specific equipment categories, too. A policy might cover your array generously but cap transformer replacement at a fraction of the real cost.
General Liability and Third-Party Risks
General liability protects you when someone else suffers bodily injury or property damage connected to your solar farm. Think of a contractor who trips over exposed conduit, a neighboring property owner whose fence is damaged during construction, or a wildfire that starts on your site and spreads. Environmental liability is a growing concern as well: chemical spills from battery storage systems or panel runoff can trigger significant environmental cleanup obligations. Most solar farm owners carry $1M/$2M general liability limits at minimum, with umbrella policies layered on top for larger installations.
Business Interruption and Loss of Revenue
Your panels don't generate revenue when they're offline. Business interruption insurance covers the income you lose during repairs after a covered event, plus ongoing fixed expenses like loan payments, lease obligations, and maintenance contracts. This coverage matters more than many owners realize. In April 2026,
California renewables curtailment hit
a record 1.46 million MWh, representing 18% of all grid-scale generation for that month. While curtailment itself isn't a covered peril, it illustrates how revenue disruptions compound quickly. Make sure your policy's indemnity period is long enough to cover realistic repair timelines, which can stretch six months or more for major equipment.
By: Dax Kastrin
Founder and Agent at ERM Insurance
California-Specific Environmental Risks
California isn't just another state for solar insurance purposes. The combination of wildfire corridors, active fault lines, and extreme weather patterns creates a risk profile that underwriters treat very differently from, say, a solar farm in Indiana.
Wildfire Protection and Mitigation Credits
Wildfire is the single biggest driver of insurance costs for California solar farms. If your project sits within a CAL FIRE High Fire-Threat District, expect higher premiums, larger deductibles, and more extensive underwriting scrutiny. The good news: insurers increasingly offer mitigation credits for proactive measures. Defensible space around your perimeter, fire-resistant vegetation management, on-site water storage, and ember-resistant equipment enclosures can all reduce your premium. Some carriers require a wildfire mitigation plan before they'll even quote a policy.
Earthquake and Seismic Activity Endorsements
Standard property policies exclude earthquake damage. You'll need a separate earthquake endorsement or a standalone seismic policy. The California Earthquake Authority
reduced its 2026 risk transfer budget by $11 million by taking advantage of softening reinsurance conditions, which may indirectly benefit commercial earthquake pricing. Industry reports from early 2026 also highlight a
shift toward integrated seismic design for solar farms, moving beyond basic wind-load resistance to specialized methodologies that account for ground motion near active fault systems. If your site is near a known fault, expect earthquake deductibles to be percentage-based rather than flat fees, with some private market policies offering deductibles as low as 5% for well-mitigated assets.
Comparing Coverage Needs: Utility-Scale vs. Commercial Projects
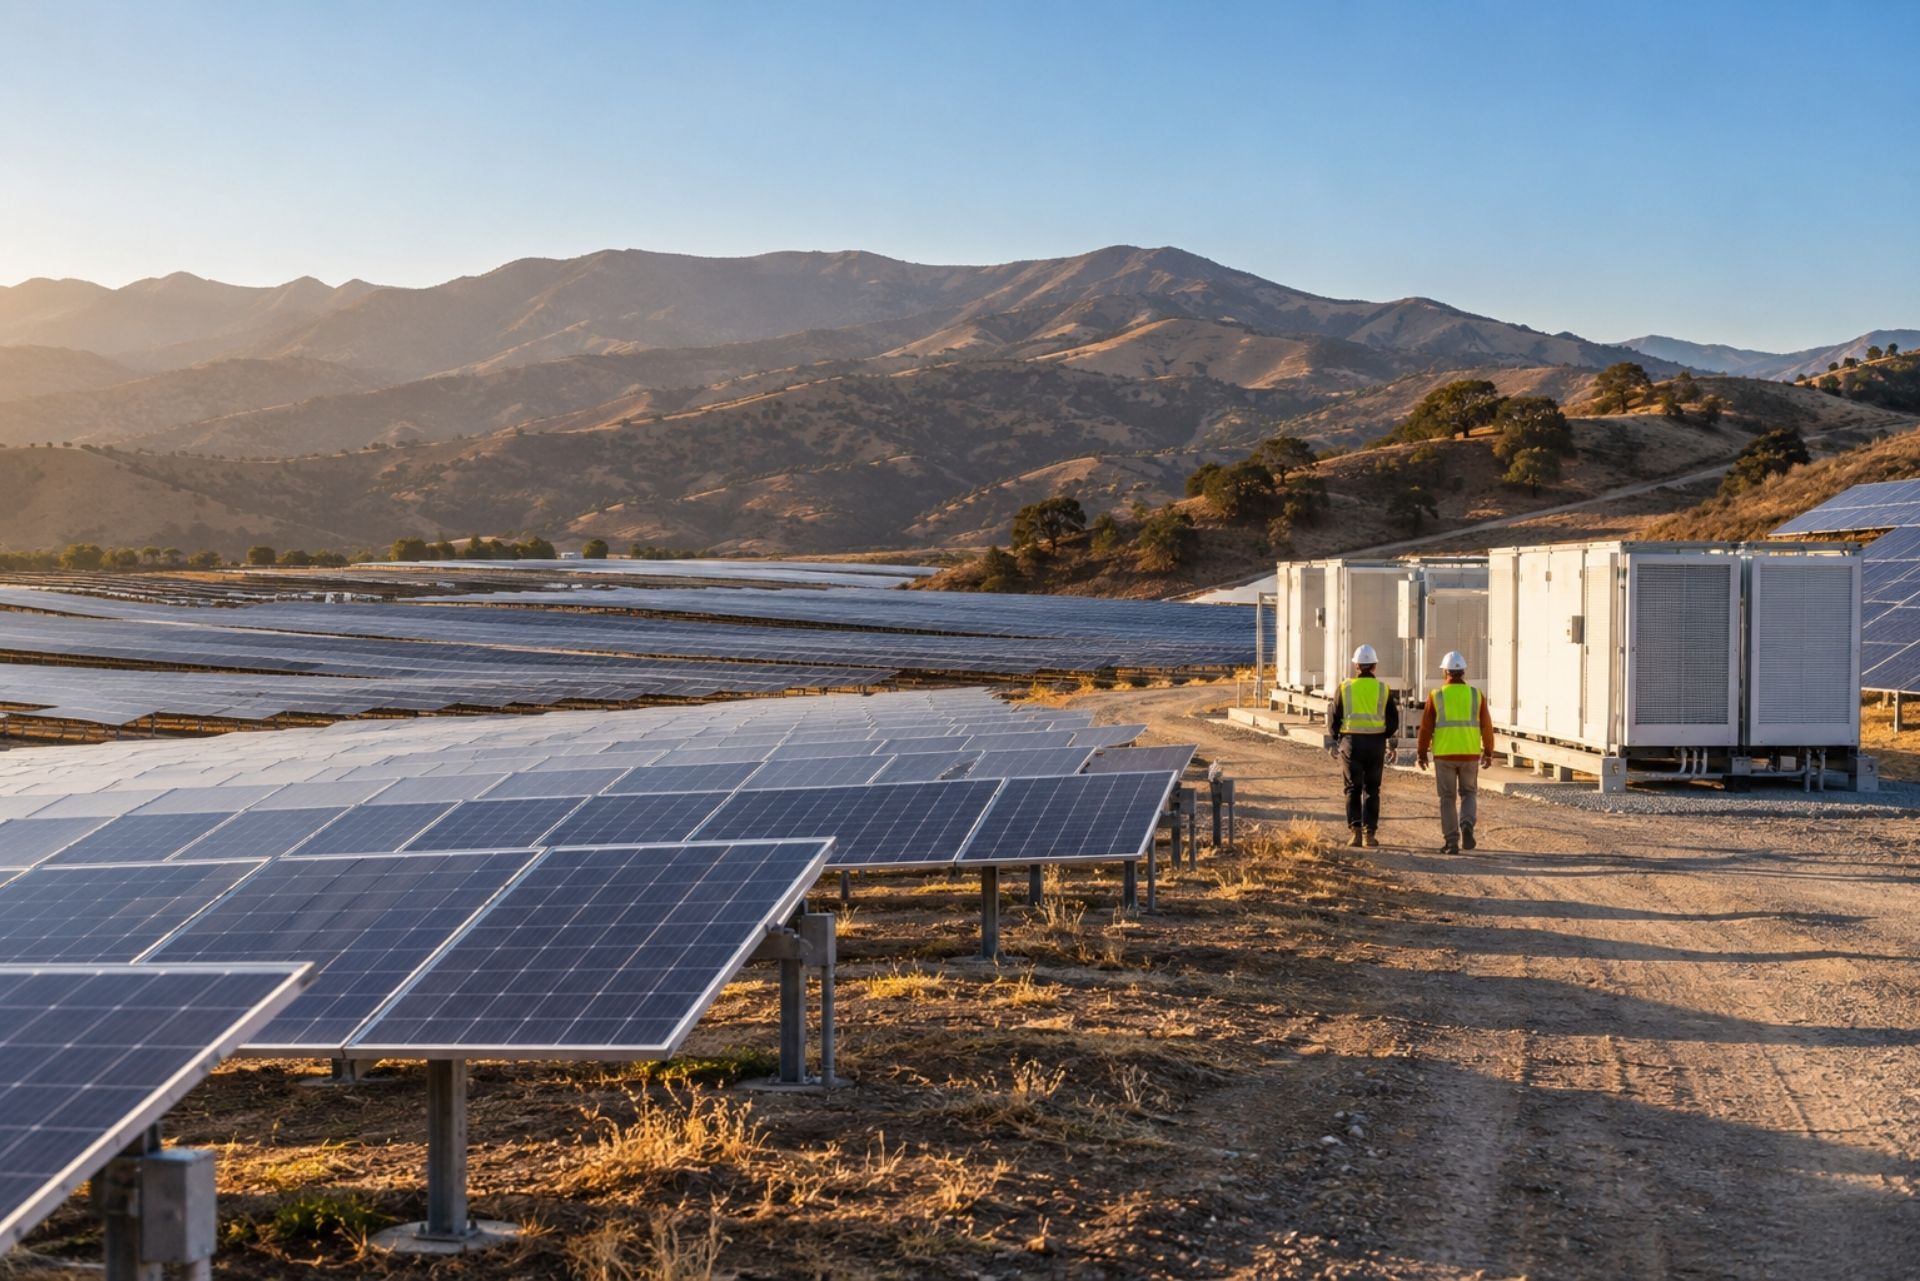
Not all solar farms need the same insurance structure. A 150 MW utility-scale plant connected to the CAISO grid has fundamentally different exposures than a 2 MW commercial rooftop array.
| Coverage Area | Utility-Scale (20+ MW) | Commercial (Under 20 MW) |
|---|---|---|
| Property Limits | $50M-$500M+ | $1M-$25M |
| Liability Limits | $5M-$25M+ umbrella | $1M-$5M umbrella |
| Business Interruption | Critical (PPA obligations) | Important (net metering credits) |
| Equipment Breakdown | Standalone policy common | Often bundled with property |
| Decommissioning Bond | Usually required by county | Sometimes required |
| Cyber Coverage | Increasingly required | Optional but recommended |
Utility-scale projects typically carry decommissioning bonds as well. These are three-party surety contracts that guarantee land restoration to its original condition at the end of a project's life. Many California counties now require them before issuing permits.
Equipment Breakdown and Specialized Endorsements
Equipment breakdown coverage, sometimes called boiler and machinery insurance, fills a critical gap. Standard property policies cover damage from external events like fire or wind. Equipment breakdown covers internal mechanical and electrical failures: a transformer that overheats, an inverter with a manufacturing defect, or a tracking system motor that seizes. For solar farms, this coverage is essential because inverters and transformers represent a huge portion of your total project cost. Replacement lead times for large inverters can run three to six months, and that downtime compounds your business interruption losses. An August 2026 Executive Order also raised concerns about grid cybersecurity and supply chain risks from foreign-produced bulk-power equipment, which could affect future equipment sourcing and insurance requirements.
Your annual premium isn't a flat rate based on system size. Insurers weigh a dozen or more variables, and understanding them gives you real negotiating power.
Equipment Type and Racking Systems
Fixed-tilt systems generally cost less to insure than single-axis trackers because trackers have more moving parts and higher wind exposure. Panel technology matters too: bifacial modules with frameless designs may carry slightly different risk profiles than traditional framed panels. The age and manufacturer of your inverters also affect pricing, since some brands have better reliability track records than others.
Proximity to High-Fire-Threat Districts (HFTD)
CAL FIRE maintains detailed maps of Tier 2 (elevated) and Tier 3 (extreme) fire threat zones. If your solar farm falls within either tier, your wildfire premium component can double or triple compared to a site outside these zones. Some insurers won't write policies for Tier 3 locations at all without comprehensive mitigation plans and third-party fire risk assessments.
Solar Insurance Questions Owners Often Ask
Do I need separate wildfire and earthquake policies, or can I bundle them? Most carriers treat wildfire and earthquake as separate endorsements or standalone policies. You can often purchase both through the same insurer, but they'll be priced and deductible-structured independently.
What's a typical deductible for a California solar farm property policy? Deductibles vary widely. For non-catastrophe perils, deductibles are often structured as a percentage of total insured value. Earthquake deductibles are also typically percentage-based, often ranging from 5% to 25% for commercial properties, and wildfire deductibles are increasingly set based on your HFTD tier.
Does my EPC contractor's insurance cover me during construction? Your contractor should carry their own general liability and builder's risk coverage, but their policy protects them, not you. You'll want an owner-controlled insurance program or a separate builder's risk policy for the construction phase. Renewable energy contractors often carry specialized policies, but always verify their coverage limits and named insured status.
How does curtailment affect my business interruption claim? It usually doesn't. Business interruption covers revenue lost due to physical damage from a covered peril. Grid curtailment, where the utility reduces your output because of oversupply, isn't a covered event under standard policies. Some parametric products are emerging to address this gap, but they're still uncommon.
Should I carry cyber liability insurance for my solar farm? If your SCADA system or monitoring platform connects to the internet, yes. A cyberattack that disables your inverters or falsifies production data can cause real financial harm. Cyber policies for solar farms are relatively affordable and increasingly expected by lenders.
How to Choose the Right Broker
Not every insurance broker understands solar energy. You want someone who has placed coverage for multiple California solar projects, knows the difference between a PPA and a net metering agreement, and has relationships with surplus lines carriers that specialize in renewable energy. Ask potential brokers how many solar farm policies they've placed in the last 12 months, which carriers they work with, and whether they can provide loss engineering support. A good broker will also help you structure your deductibles strategically, sometimes accepting a higher property deductible to free up budget for broader business interruption coverage.
Common Coverage Gaps That Catch Owners Off Guard
Three gaps trip up solar farm owners more than any others. First, flood exclusions: standard property policies exclude flood damage, and many solar farms in California's Central Valley sit in or near flood zones. Second, panel degradation: insurance covers sudden damage, not gradual performance decline. If your panels lose efficiency over time, that's a warranty issue, not an insurance claim. Third, transmission line damage between your interconnection point and the utility substation. Some policies stop coverage at your meter, leaving a critical stretch of infrastructure uninsured.
Regulatory and Bonding Requirements in California
California imposes specific insurance and bonding requirements that vary by county and project size. Most utility-scale projects require decommissioning bonds, and some counties mandate minimum liability limits as a condition of your conditional use permit. The California Department of Insurance also regulates surplus lines placements, which is relevant because many solar farm policies are written through non-admitted carriers. Make sure your broker files the proper surplus lines documentation, or you could face penalties. Environmental liability requirements are also tightening as regulators pay closer attention to battery storage systems and panel recycling obligations.
Annual Policy Review Checklist
Your insurance needs change as your project ages. Run through this checklist every year before renewal:
- Verify that your total insured value reflects current replacement costs, not original installation costs
- Update your equipment schedule if you've replaced inverters, added battery storage, or expanded capacity
- Review your business interruption indemnity period against realistic repair timelines
- Confirm that your wildfire mitigation measures still qualify for premium credits
- Check whether your decommissioning bond amount still satisfies county requirements
- Ask your broker about new products, especially parametric weather coverage and cyber liability
Making the Right Choice for Your Investment
Solar farm insurance in California isn't a single policy you buy and forget. It's a layered program that needs to account for wildfire, earthquake, equipment failure, liability, revenue loss, and regulatory compliance, all at once. The owners who pay the least relative to their risk are the ones who invest in mitigation, choose brokers with genuine solar experience, and review their coverage annually.
Your next step is straightforward: get your current policy reviewed by a broker who specializes in renewable energy. If you don't have coverage yet, start by mapping your site against CAL FIRE's HFTD zones and identifying your top three exposures. That gives you a concrete starting point for conversations with insurers, and it puts you in a much stronger position to negotiate terms that actually protect your investment.
About The Author:
Dax Kastrin
As Founder and Agent at ERM Insurance, I’m committed to helping clients understand and manage risk through clear, straightforward coverage solutions. With professional designations as an Accredited Advisor in Insurance (AAI) and Associate in General Insurance (AINS), I focus on delivering dependable protection and personalized service for every individual and business I work with.
Your Business Insurance Solutions
Workers’ Compensation Insurance
Protect your workers from significant financial losses if they are injured or disabled while performing their duties as an employee.
Cyber Liability Insurance
Safeguard your business against financial losses from data breaches, especially those that involve sensitive customer information and other unforeseen cyber events, like cybercrime.
Directors & Officers Liability
Protect your C-suite officers and board members, as well as the companies they represent if they are the subject of a claim or investigation from their duties.
General Liability Insurance
Guard your business against the cost of claims that can be filed due to bodily injury to a third party, damage to third-party property, lawsuits, and more.
Business Owners Insurance
Reduce the cost of premiums by getting a business owner’s insurance, a coverage plan that combines commercial property insurance and general liability insurance.
Commercial Auto Insurance
Guard your business against financial losses from accidents involving company vehicles. Commercial auto insurance provides for bodily injury liability and property damage.
Commercial Property Insurance
Recover from financial losses involving damage to your physical assets, including furniture, physical building, office space, inventory, landscaping and fencing, signage, and more.
Lessor's Risk Insurance
Get coverage for your rental properties. A lessor’s risk insurance covers financial losses from acts of vandalism, litigation costs for lawsuits, theft of property owned by your tenants, and more.
Product Liability Insurance
Protect your companies from claims made against the goods you provide. This covers injuries caused by malfunctions of products, design defects, and more.
Choose Elemental Risk Management Today
Get a Plan Suited to Your Business
ERM assesses the risks that your company faces, as well as your industry, operations, workforce, and more.
Recover Quickly
With business insurance coverage, you’ll bounce back from adverse events that could have left your business on the brink of bankruptcy.
Avoid Overpaying
Through customized solutions, your business will get adequate coverage without unnecessary costs. We’ll keep premiums cost-effective.
Our Testimonials
Hear from our clients
“We recently changed our business insurance after over 20 years, and we couldn't be happier. We didn't realize how poor the service was, how unresponsive, and slow the service was of our previous carrier. Dax and his team have gone above and beyond to answer every question our business had, to ensure that we had the coverage we needed, and fully understood everything we were getting. Not only did we save money, but we have saved a lot of time with the quick responsiveness of this team. They are exceptional. Would Highly recommend, and provide references."
Laura Harrison
May 2021
"I love working with the ERM crew! They are always super inquisitive and willing to learn/ask questions to provide their clients with the best possible insurance solution. I would definitely recommend them to anyone looking for advice on their current policies and coverage."
Nicole Limpert
May 2021
“Elemental Risk Management has been our insurance agent for 2 years now. They are consistently shopping for us to have the very best quality of coverage, as well as the best rates available. They saved our company over $20,000.00 in premiums our first year doing business with them. They are also quick to respond to any need (COI's, accident reporting, etc.). I recommend the team at ERM very highly!
Ramona Mills
June 2021