Colorado Self Storage Facility Insurance
8:30am - 5:00pm Mon-Fri
Will Reply in 15min*
Over 180+ commercial clients covered
100% customer satisfaction guaranteed
Over 10 years of business insurance experience
Owning a self storage facility in Colorado means dealing with risks that most
commercial property owners don't think about until it's too late. A single hailstorm along the Front Range can damage dozens of unit doors in one afternoon. A tenant's belongings can be destroyed by a burst pipe, and suddenly you're fielding angry calls and legal threats. Colorado's
insurance market has been volatile in recent years, with
property insurance rates in the state
surging by 100% between 2018 and 2024, far outpacing national averages. That makes it more important than ever to understand exactly what coverage you need, what you can skip, and how to keep premiums from eating into your margins. Whether you're running a 50-unit facility in Pueblo or a climate-controlled operation in Denver, the right insurance for your Colorado self storage facility isn't optional. It's the foundation that keeps your business standing after the unexpected hits.
Essential Insurance Coverage for Colorado Storage Facilities
Every storage facility faces a core set of risks: someone slips on icy pavement, a fire guts a building, or a disgruntled tenant claims you damaged their property. The coverage you carry determines whether those events are minor inconveniences or business-ending disasters. Colorado's climate and legal environment add layers of complexity that generic commercial policies often miss. Getting the basics right means understanding three distinct coverage areas and how they work together to protect your operation.
General Liability and Property Protection
General liability insurance is the bedrock of any commercial policy. It covers third-party bodily injury and property damage claims, meaning if a customer trips over a speed bump in your parking lot and breaks a wrist, your policy responds. Most facilities carry $1 million per occurrence and $2 million aggregate limits, though high-traffic locations may need more.
Property insurance covers the buildings themselves, including unit walls, roofing, gates, and office structures. In Colorado, you'll want to confirm your policy covers the actual replacement cost rather than a depreciated value. A metal storage building that cost $400,000 to construct five years ago could cost $520,000 or more to replace in 2026, given rising material and labor costs. Business income coverage (sometimes called business interruption) is also worth adding. If a wildfire forces you to close for three months, this coverage replaces lost rental income during the rebuild.
Customer Goods Legal Liability
Here's a coverage gap that catches many facility owners off guard. Standard property insurance covers your buildings and equipment, but it doesn't cover what tenants store inside the units. Customer goods legal liability fills that gap. It protects you when a tenant's belongings are damaged due to something you're legally responsible for, like a roof leak you failed to repair or a pest infestation you ignored.
This coverage typically ranges from $5,000 to $25,000 per unit, with aggregate limits between $250,000 and $1 million depending on your facility's size. It's not the same as tenant insurance (which the tenant buys). Think of it as your safety net for situations where negligence on your part leads to a loss. Without it, you're paying out of pocket for every damaged sofa, ruined photo album, or waterlogged electronics set.
Sale and Disposal Liability
Colorado law allows facility operators to sell a tenant's belongings after following specific lien procedures. But what happens if you sell items that turn out to belong to someone else? Or if you dispose of property before the legally required waiting period ends? Sale and disposal liability coverage protects you from lawsuits arising from these situations.
This is a niche coverage, but it's one that storage operators in Colorado need. Mistakes during the lien sale process, even honest ones, can result in claims for the full value of the disposed goods. A single wrongful sale lawsuit can easily exceed $10,000 in legal fees alone, even if you ultimately win.
By: Dax Kastrin
Founder and Agent at ERM Insurance
Colorado isn't like running a storage facility in Florida or Texas. The state's unique combination of extreme weather events and specific self-storage legislation creates risks that demand tailored coverage.
Weather-Related Risks: Hail, Snow, and Wildfire
The Front Range is one of the most hail-prone regions in the country. A severe hailstorm can dent or destroy metal roll-up doors across an entire facility in minutes. Snow loads in mountain communities can collapse older roofs, and wildfire risk continues to grow along the urban-wildland interface. The Marshall Fire in late 2021 destroyed over 1,000 structures in Boulder County, a reminder that wildfire isn't just a mountain problem.
Your property policy should specifically address hail damage, snow load collapse, and wildfire. Some carriers exclude or sublimit wildfire coverage in high-risk zones, so read your declarations page carefully. If your facility sits in a WUI (wildland-urban interface) area, expect higher premiums and potentially separate wildfire deductibles. Colorado legislators have been working to make property insurance more affordable statewide, but storage operators in fire-prone areas still face steep costs.
Compliance with the Colorado Self-Service Storage Facility Act
Colorado's Self-Service Storage Facility Act (C.R.S. 38-21.5-101 through 38-21.5-109) governs your rights and obligations as a facility owner. It outlines lien procedures, notice requirements, and tenant protections. A bill recently introduced to the Colorado 68th General Assembly proposes updates to these lien laws, which could change how you handle delinquent accounts and property disposal.
Non-compliance with the Act doesn't just expose you to lawsuits. It can also void certain insurance protections. If your carrier determines you violated state law during a lien sale, they may deny a related claim. Keeping your lease agreements, notice procedures, and sale processes aligned with current Colorado law is just as important as having the right policy in place.
Comparing Policy Tiers and Coverage Limits
Not all storage facility insurance policies are created equal. The difference between a bare-bones policy and a comprehensive one can mean the difference between full recovery and financial ruin after a major loss.
Comparison Table: Standard vs. Comprehensive Protection
| Coverage Feature | Standard Policy | Comprehensive Policy |
|---|---|---|
| General Liability | $1M per occurrence / $2M aggregate | $1M per occurrence / $2M aggregate |
| Property Coverage | Actual cash value | Replacement cost |
| Customer Goods Liability | Not included | $10,000-$25,000 per unit |
| Sale and Disposal Liability | Not included | Included |
| Business Interruption | 3 months max | 12 months |
| Hail/Wind Deductible | 2-5% of insured value | 1-2% of insured value |
| Wildfire Coverage | Sublimited or excluded | Full coverage with separate deductible |
| Cyber Liability | Not included | $100K-$500K |
| Estimated Annual Premium | $2,500-$5,000 | $6,000-$15,000+ |
The standard tier works for small facilities in low-risk areas with minimal exposure. But most Colorado operators, especially those along the Front Range or in wildfire zones, need comprehensive protection. The cost difference is significant, but so is the gap in coverage. Colorado's commercial insurance trends for 2026 point toward continued rate increases, making it even more critical to compare quotes carefully rather than defaulting to the cheapest option.
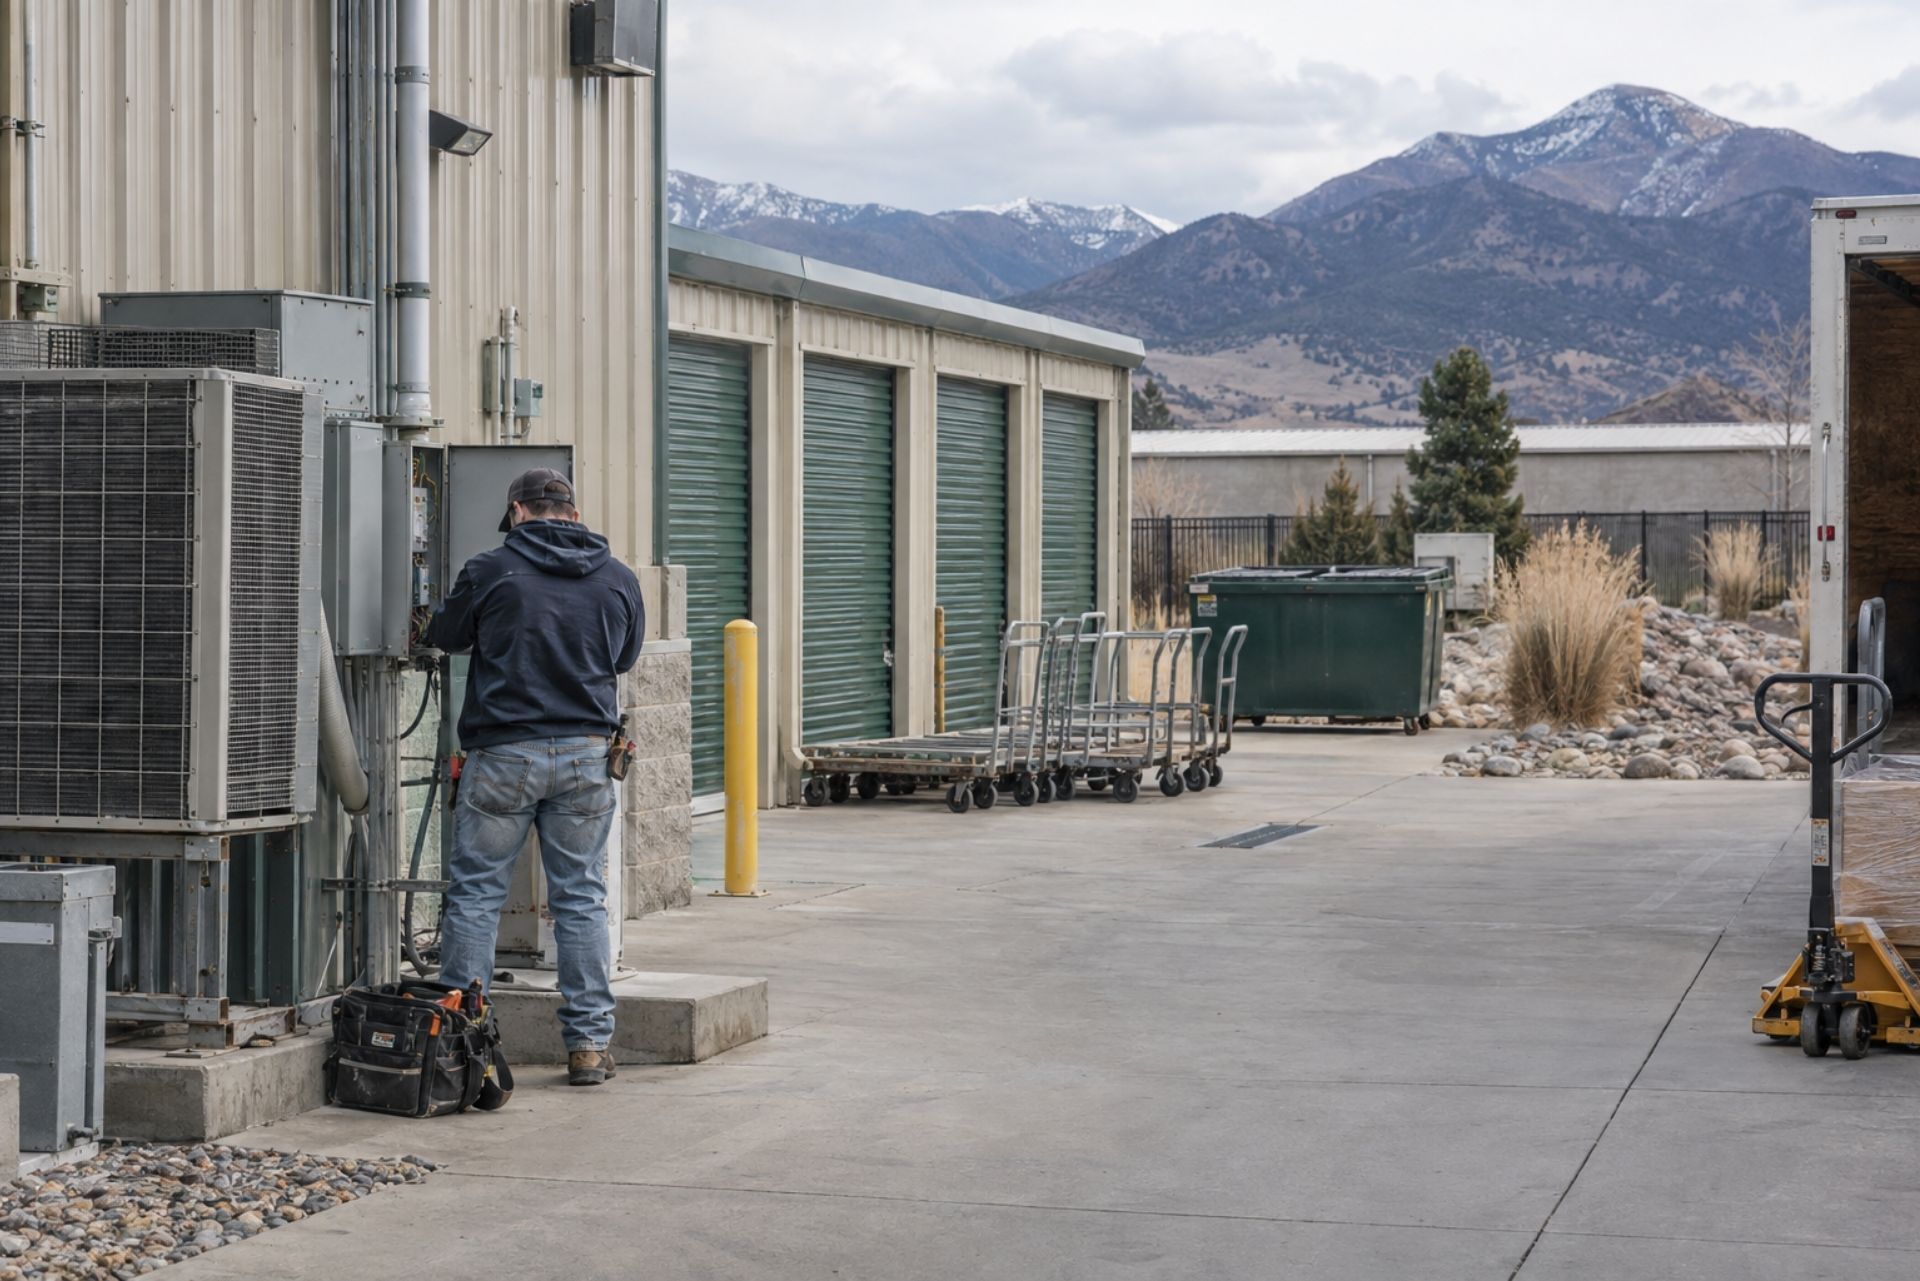
Rising premiums don't mean you're powerless. Several practical steps can reduce what you pay without sacrificing the coverage you need.
Security Upgrades and Gated Access
Insurance carriers price risk. The more you reduce the likelihood of theft, vandalism, and unauthorized access, the lower your premiums. Gated access with individual keypad codes, 24/7 surveillance cameras with cloud storage, and motion-activated lighting are the three upgrades that consistently produce the biggest premium discounts.
Some carriers offer 5-15% discounts for facilities that meet specific security standards. Ask your agent what qualifies. Even a modest investment of $10,000-$20,000 in upgraded cameras and access controls can pay for itself within two to three years through premium savings alone. Colorado's property mitigation initiatives also encourage physical improvements that reduce weather-related risk, which can further lower your costs.
Implementing Tenant Insurance Programs
Requiring tenants to carry their own storage insurance, or offering a tenant protection plan through your facility, does two things. First, it shifts the financial burden of tenant property losses away from your policy. Second, it generates ancillary revenue. Many facility management platforms now integrate tenant insurance programs that add $10-$15 per month to each tenant's bill.
From an insurance perspective, facilities with mandatory tenant insurance programs often qualify for lower customer goods liability premiums because the carrier's exposure drops significantly. It's a win for you, a win for the tenant (who now has coverage they probably didn't have before), and a win for your insurer.
Common Questions About Storage Facility Insurance
FAQs: Costs, Claims, and Requirements
Is self storage facility insurance required by law in Colorado? Colorado doesn't mandate that facility owners carry insurance, but your lender or landlord almost certainly does. Operating without coverage is a financial gamble most owners can't afford.
How much does insurance for a Colorado storage facility typically cost? Premiums range from $2,500 for basic coverage on a small facility to $15,000 or more for comprehensive protection on a larger operation. Location, building age, security features, and claims history all affect pricing.
Does my policy cover tenant belongings? Not automatically. You need customer goods legal liability coverage for situations where you're at fault, and tenants should carry their own renter's or storage insurance for everything else.
What's the most common claim for storage facilities? Water damage, hands down. Roof leaks, burst pipes, and flooding account for more claims than fire, theft, and vandalism combined. Regular maintenance is your best defense.
Can I bundle my storage facility insurance with other commercial properties? Yes, and you should. Multi-location or multi-property policies often come with volume discounts of 10-20%.
How often should I review my policy?
At least once a year, and any time you expand, renovate, or add units. A facility you insured for $800,000 two years ago might need $1 million in coverage today.
Making the Right Choice for Your Facility
Getting the right self storage insurance in Colorado comes down to understanding your specific risks and matching them with appropriate coverage. A facility in Colorado Springs faces different threats than one in Steamboat Springs, and your policy should reflect that. Don't default to the cheapest quote. Instead, work with an agent who understands the storage industry and Colorado's unique risk profile.
Review your policy annually, invest in security and mitigation upgrades that earn premium discounts, and make tenant insurance a non-negotiable part of your lease agreement. Governor Polis has
unveiled plans aimed at cutting property insurance costs for Colorado residents, but commercial operators need to take their own proactive steps. The storage industry in Colorado is growing, and protecting your investment with the right coverage isn't just smart business. It's the only way to build something that lasts.
About The Author:
Dax Kastrin
As Founder and Agent at ERM Insurance, I’m committed to helping clients understand and manage risk through clear, straightforward coverage solutions. With professional designations as an Accredited Advisor in Insurance (AAI) and Associate in General Insurance (AINS), I focus on delivering dependable protection and personalized service for every individual and business I work with.
Your Business Insurance Solutions
Workers’ Compensation Insurance
Protect your workers from significant financial losses if they are injured or disabled while performing their duties as an employee.
Cyber Liability Insurance
Safeguard your business against financial losses from data breaches, especially those that involve sensitive customer information and other unforeseen cyber events, like cybercrime.
Directors & Officers Liability
Protect your C-suite officers and board members, as well as the companies they represent if they are the subject of a claim or investigation from their duties.
General Liability Insurance
Guard your business against the cost of claims that can be filed due to bodily injury to a third party, damage to third-party property, lawsuits, and more.
Business Owners Insurance
Reduce the cost of premiums by getting a business owner’s insurance, a coverage plan that combines commercial property insurance and general liability insurance.
Commercial Auto Insurance
Guard your business against financial losses from accidents involving company vehicles. Commercial auto insurance provides for bodily injury liability and property damage.
Commercial Property Insurance
Recover from financial losses involving damage to your physical assets, including furniture, physical building, office space, inventory, landscaping and fencing, signage, and more.
Lessor's Risk Insurance
Get coverage for your rental properties. A lessor’s risk insurance covers financial losses from acts of vandalism, litigation costs for lawsuits, theft of property owned by your tenants, and more.
Product Liability Insurance
Protect your companies from claims made against the goods you provide. This covers injuries caused by malfunctions of products, design defects, and more.
Choose Elemental Risk Management Today
Get a Plan Suited to Your Business
ERM assesses the risks that your company faces, as well as your industry, operations, workforce, and more.
Recover Quickly
With business insurance coverage, you’ll bounce back from adverse events that could have left your business on the brink of bankruptcy.
Avoid Overpaying
Through customized solutions, your business will get adequate coverage without unnecessary costs. We’ll keep premiums cost-effective.
Our Testimonials
Hear from our clients
“We recently changed our business insurance after over 20 years, and we couldn't be happier. We didn't realize how poor the service was, how unresponsive, and slow the service was of our previous carrier. Dax and his team have gone above and beyond to answer every question our business had, to ensure that we had the coverage we needed, and fully understood everything we were getting. Not only did we save money, but we have saved a lot of time with the quick responsiveness of this team. They are exceptional. Would Highly recommend, and provide references."
Laura Harrison
May 2021
"I love working with the ERM crew! They are always super inquisitive and willing to learn/ask questions to provide their clients with the best possible insurance solution. I would definitely recommend them to anyone looking for advice on their current policies and coverage."
Nicole Limpert
May 2021
“Elemental Risk Management has been our insurance agent for 2 years now. They are consistently shopping for us to have the very best quality of coverage, as well as the best rates available. They saved our company over $20,000.00 in premiums our first year doing business with them. They are also quick to respond to any need (COI's, accident reporting, etc.). I recommend the team at ERM very highly!
Ramona Mills
June 2021