New Mexico Wind Farm Insurance
8:30am - 5:00pm Mon-Fri
Will Reply in 15min*
Over 180+ commercial clients covered
100% customer satisfaction guaranteed
Over 10 years of business insurance experience
New Mexico's wind energy sector has grown fast. The state now runs
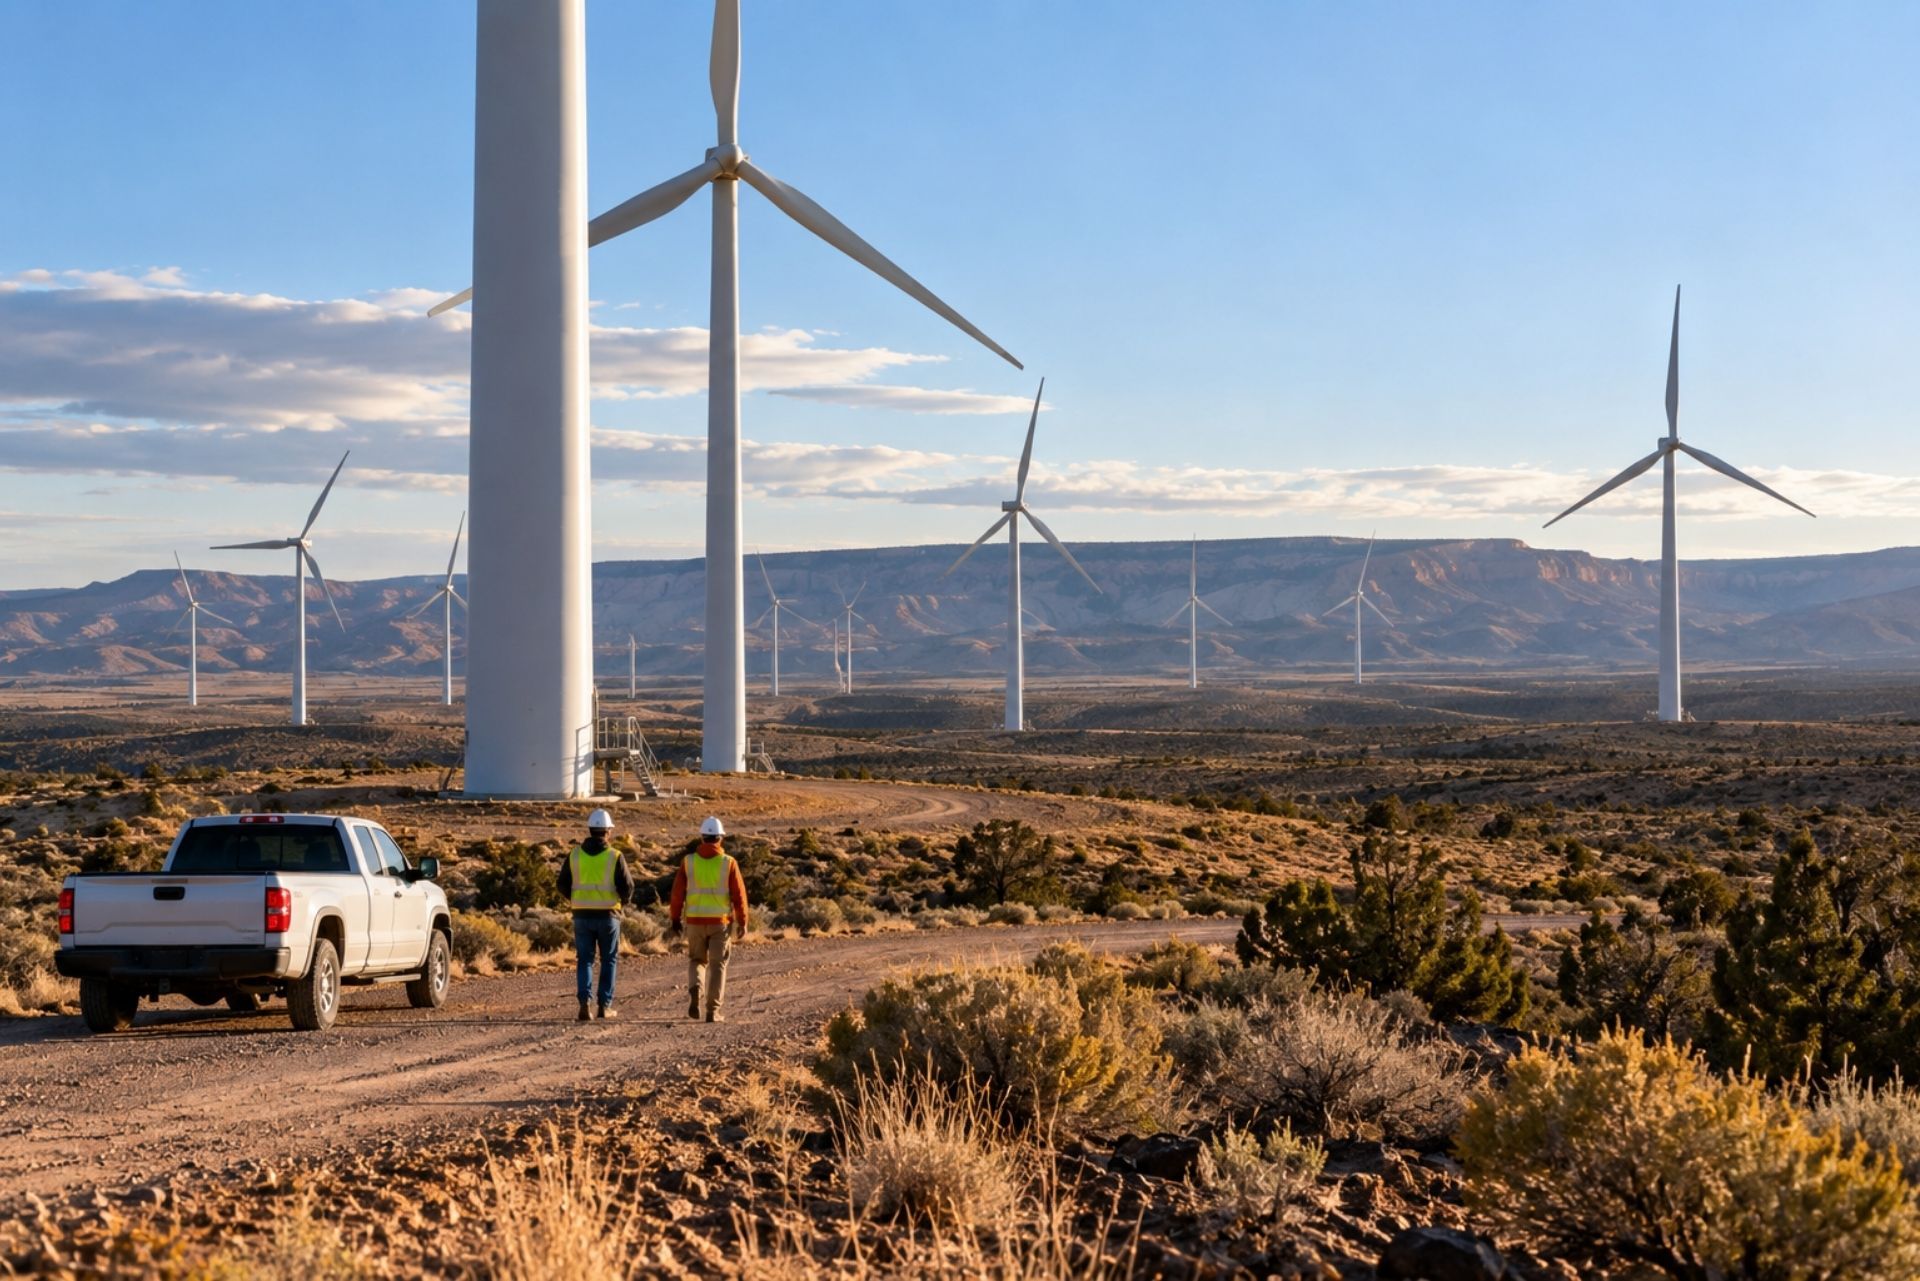
31 utility-scale wind farms with a combined capacity of 8,079 MW, representing 45 percent of its total capacity mix. That kind of scale brings serious financial exposure. A single turbine blade can cost $200,000 or more to replace, and a bad monsoon season or wildfire event can knock multiple units offline for months. If you own, operate, or invest in wind generation here, understanding
wind farm insurance in New Mexico is not optional: it's the difference between a recoverable setback and a financial disaster. This guide walks through the specific hazards your project faces, the coverages that actually matter, and the gaps that catch operators off guard. From high winds and icing to turbine breakdown, business interruption, and liability, we'll cover what you need to protect your assets and your revenue stream in one of the country's most active wind corridors.
Understanding the Unique Risks to New Mexico Wind Farms
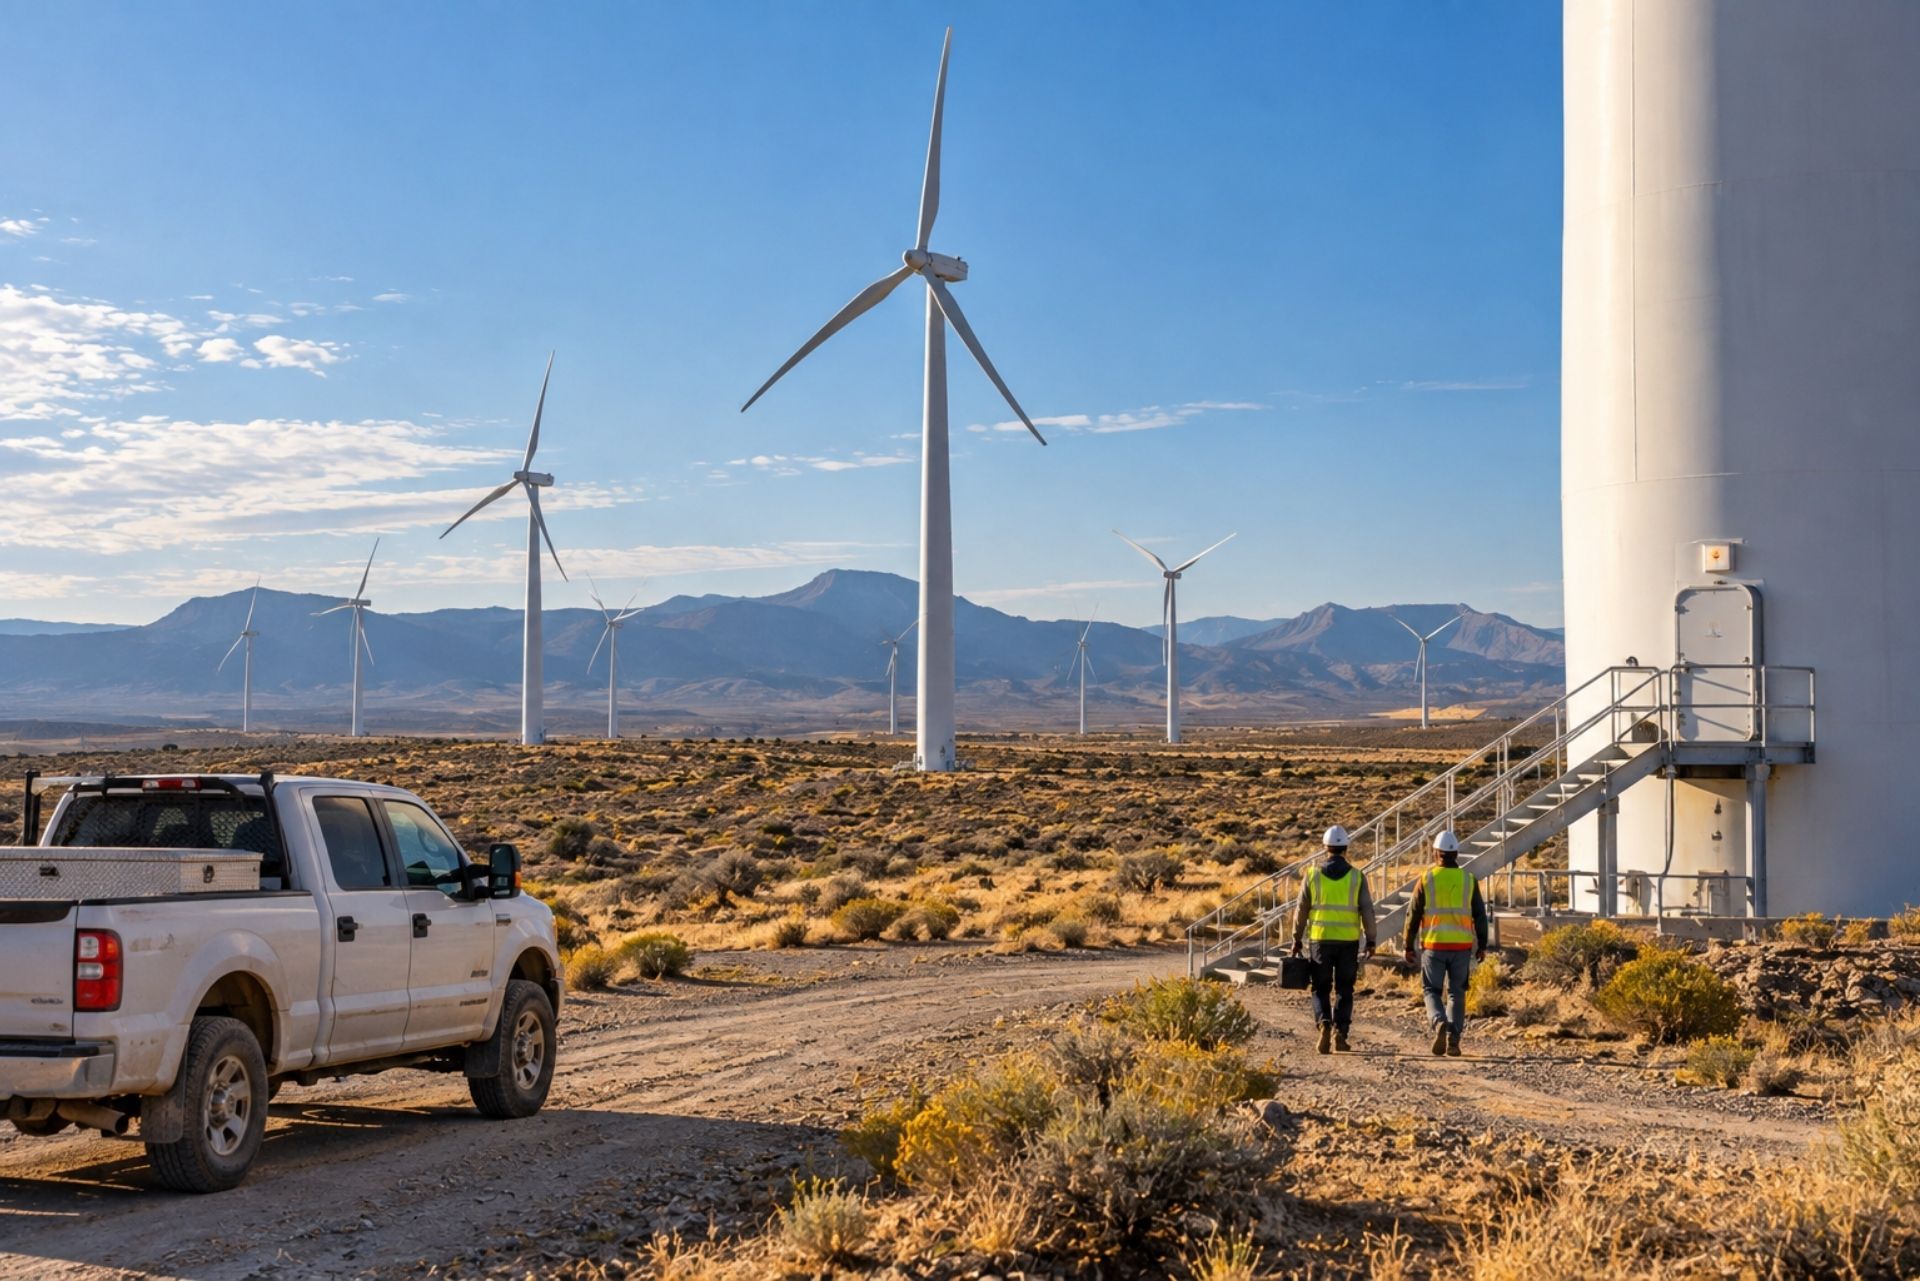
New Mexico's geography creates a risk profile unlike anything you'd find in the Midwest or along the Gulf Coast. The state's wind resources sit in high-desert terrain, where extreme temperature swings, low humidity, and intense solar radiation wear on mechanical components year-round. Turbines here deal with abrasive particulate matter, rapid pressure changes, and elevation-related stress that accelerates fatigue on gearboxes and bearings.
The SunZia Wind Project became fully operational in June 2026, deploying 916 turbines across Lincoln, San Miguel, and Torrance counties. A project of that scale illustrates just how concentrated the financial risk has become in a handful of New Mexico counties. When you're insuring assets spread across remote high-desert terrain, access for repairs, parts logistics, and emergency response all factor into your risk equation.
Environmental Hazards: Dust Storms and High-Desert Heat
Dust storms in eastern New Mexico can reduce visibility to near zero and blast turbine blades with fine silica particles at high velocity. Over time, this erosion degrades the aerodynamic surface of blades, reducing efficiency and eventually requiring costly repairs or full replacement. High-desert heat compounds the problem: ambient temperatures above 100 degrees Fahrenheit stress cooling systems on gearboxes and generators, increasing the likelihood of mechanical failure during peak summer months.
Insurers pay close attention to these environmental factors. A turbine sitting at 6,500 feet elevation in Torrance County faces different wear patterns than one at sea level in Texas. Your policy needs to reflect those realities, not just generic "wind turbine" risk assumptions.
Lightning Strikes and Monsoon Season Challenges
New Mexico's monsoon season, typically running from late June through September, brings intense thunderstorms with frequent cloud-to-ground lightning. Wind turbines are the tallest structures for miles in most of the state's wind corridors, making them natural lightning targets. A single strike can destroy a blade, fry control electronics, or damage the generator, and lightning damage causes the longest average downtime for wind farms at 233 days per closed claim.
That's nearly eight months of lost production from one event. Monsoon storms also bring hail, which has become a
primary loss driver for the insurance industry rather than the secondary peril it was once considered. Your coverage needs to account for both the direct physical damage and the extended revenue loss that follows.
By: Dax Kastrin
Founder and Agent at ERM Insurance
Essential Insurance Coverages for Wind Operations
Getting the right insurance for a New Mexico wind farm means layering several distinct policies. No single product covers everything, and the gaps between policies are where operators get burned. Think of your insurance program as a system: property, equipment breakdown, liability, and business interruption all need to work together without overlaps that waste premium dollars or gaps that leave you exposed.
One thing to keep in mind: the energy insurance market in mid-2026 saw rates for well-managed accounts decrease by an average of 1.2 percent, while broader U.S. property rates fell by 7.1 percent. That spread tells you something. Energy assets are priced differently because insurers know a single catastrophic event can reverse months of collected premium. Your loss history, maintenance records, and risk mitigation practices directly affect what you'll pay.
Property and Equipment Breakdown Protection
Property coverage protects the physical assets: turbines, towers, foundations, substations, underground cabling, and control buildings. Equipment breakdown (sometimes called machinery breakdown) is a separate but related coverage that handles failures due to mechanical or electrical malfunction rather than external events. A gearbox that seizes because of a bearing defect is an equipment breakdown claim, not a property claim. If your policy doesn't include both, you've got a hole.
Pay attention to how your policy defines "covered equipment" and whether it includes SCADA systems, transformers, and meteorological towers. Some policies exclude foundations or underground infrastructure unless you specifically add them. We've seen operators assume their $2 million substation was covered under a blanket property policy, only to discover it was excluded after a transformer failure.
General Liability vs. Professional Liability
General liability covers bodily injury and property damage claims from third parties: a landowner whose fence is damaged during construction, a visitor injured on-site, or a trespasser struck by ice thrown from a blade. Professional liability (errors and omissions) covers claims arising from design, engineering, or consulting services. If you're an owner-operator, you likely need general liability. If you also provide engineering or project management services to other developers, professional liability becomes essential.
Don't confuse these with pollution liability, which you'll want if your site has any fuel storage, battery systems, or transformer oil that could contaminate soil or groundwater.
Comparison of Coverage Tiers for Renewable Energy
Basic vs. Comprehensive Wind Farm Protection Table
| Coverage Element | Basic Tier | Comprehensive Tier |
|---|---|---|
| Named-peril property damage | Included | Included |
| All-risk property damage | Not included | Included |
| Equipment/machinery breakdown | Optional add-on | Included |
| Lightning and hail damage | Limited sublimits | Full replacement cost |
| Business interruption | Included | Included |
| Contingent business interruption | Not included | Included |
| General liability ($1M/$2M) | Included | Included |
| Pollution liability | Not included | Optional add-on |
| Cyber/SCADA coverage | Not included | Included |
| Debris removal | Sublimited | Higher sublimits |
The difference between basic and comprehensive tiers isn't just about premium cost. It's about how long you can survive a major loss event. A basic policy with a six-month business interruption indemnity period won't help if your lightning-damaged turbine takes 233 days just to close the claim, let alone complete repairs and return to production.
Mitigating Business Interruption and Revenue Loss
Revenue loss is often the largest financial impact of a wind farm incident, exceeding the cost of physical repairs. Your turbines generate income every hour they spin, and when they stop, your power purchase agreement obligations don't pause. Business interruption insurance replaces lost revenue during the period your equipment is down, but the details of your policy matter enormously.
Watch the waiting period (deductible expressed in days rather than dollars), the indemnity period (how long coverage lasts), and how "lost revenue" is calculated. Some policies use historical production data, others use projected output based on wind resource assessments. If your site had a below-average wind year before the loss, a historical calculation could shortchange your payout.
Contingent Business Interruption for Supply Chain Delays
Contingent business interruption covers revenue losses caused by problems at a supplier's or customer's location, not your own. If your turbine manufacturer's factory floods and your replacement gearbox is delayed by four months, contingent BI picks up the additional lost revenue beyond what standard BI covers. Given global supply chain volatility for specialized turbine components, this coverage has become increasingly valuable for New Mexico operators.
Protecting Against Transmission and Grid Failure
Your turbines might be spinning perfectly, but if the transmission line to the grid goes down or the utility curtails your output, you're still losing money. Transmission infrastructure in rural New Mexico can be vulnerable to wildfires, ice storms, and even vehicle collisions with power poles. Some comprehensive policies cover grid-related losses, but many don't. Ask your broker specifically about transmission line coverage and forced curtailment provisions. These are the gaps that quietly cost operators hundreds of thousands of dollars.
Common Questions About Insuring Wind Farms
FAQ: How do I know if my turbines are fully covered?
Request a detailed schedule of covered equipment from your insurer and compare it against your actual asset register. Look specifically for exclusions on foundations, underground cabling, SCADA systems, and meteorological towers. If an asset isn't listed, it likely isn't covered.
FAQ: Does insurance cover damage from New Mexico dust storms?
Most all-risk property policies cover windstorm damage, which includes dust storms. Named-peril policies may not. The bigger issue is gradual blade erosion from particulate exposure, which insurers typically classify as wear and tear, not a covered peril. You'll need to budget for blade maintenance separately.
FAQ: What happens if a turbine fire spreads to nearby land?
Your general liability policy should cover third-party property damage caused by a fire originating at your site. That said, check your policy limits carefully. Wildfire in New Mexico can spread across thousands of acres quickly, and a $1 million general liability limit may not be enough if the fire reaches structures or agricultural land. Higher limits or an umbrella policy are worth the added premium.
FAQ: Can I get coverage for lost income when the wind stops blowing?
No. Business interruption insurance covers revenue loss due to physical damage to covered equipment, not low-wind periods. Some operators hedge wind variability through financial instruments like weather derivatives, but those aren't insurance products. Your BI policy triggers only when a covered event physically prevents your turbines from generating power.
Making the Right Choice for Your Energy Project
New Mexico's wind industry carries real financial weight, and protecting that investment requires more than a standard property policy. The combination of lightning exposure, monsoon hail, dust erosion, and remote-site logistics creates a risk environment that demands specialized coverage. The market remains sensitive to single significant loss events, meaning one bad claim season could tighten pricing and availability for everyone.
Start by getting a full risk assessment from a broker who specializes in renewable energy, not a generalist commercial agent. Review your asset schedule line by line. Stress-test your business interruption provisions against realistic downtime scenarios, especially that 233-day lightning claim average. And don't skip contingent BI or transmission coverage just to save on premium: those are the exposures that create the largest uninsured losses.
Your wind farm is a long-term investment. Your insurance program should match that horizon. Get quotes from at least three carriers, compare not just price but policy language, and revisit your coverage annually as your site ages and the market shifts. The right policy won't just protect your turbines. It'll protect your ability to keep generating clean energy and revenue for decades.
About The Author:
Dax Kastrin
As Founder and Agent at ERM Insurance, I’m committed to helping clients understand and manage risk through clear, straightforward coverage solutions. With professional designations as an Accredited Advisor in Insurance (AAI) and Associate in General Insurance (AINS), I focus on delivering dependable protection and personalized service for every individual and business I work with.
Your Business Insurance Solutions
Workers’ Compensation Insurance
Protect your workers from significant financial losses if they are injured or disabled while performing their duties as an employee.
Cyber Liability Insurance
Safeguard your business against financial losses from data breaches, especially those that involve sensitive customer information and other unforeseen cyber events, like cybercrime.
Directors & Officers Liability
Protect your C-suite officers and board members, as well as the companies they represent if they are the subject of a claim or investigation from their duties.
General Liability Insurance
Guard your business against the cost of claims that can be filed due to bodily injury to a third party, damage to third-party property, lawsuits, and more.
Business Owners Insurance
Reduce the cost of premiums by getting a business owner’s insurance, a coverage plan that combines commercial property insurance and general liability insurance.
Commercial Auto Insurance
Guard your business against financial losses from accidents involving company vehicles. Commercial auto insurance provides for bodily injury liability and property damage.
Commercial Property Insurance
Recover from financial losses involving damage to your physical assets, including furniture, physical building, office space, inventory, landscaping and fencing, signage, and more.
Lessor's Risk Insurance
Get coverage for your rental properties. A lessor’s risk insurance covers financial losses from acts of vandalism, litigation costs for lawsuits, theft of property owned by your tenants, and more.
Product Liability Insurance
Protect your companies from claims made against the goods you provide. This covers injuries caused by malfunctions of products, design defects, and more.
Choose Elemental Risk Management Today
Get a Plan Suited to Your Business
ERM assesses the risks that your company faces, as well as your industry, operations, workforce, and more.
Recover Quickly
With business insurance coverage, you’ll bounce back from adverse events that could have left your business on the brink of bankruptcy.
Avoid Overpaying
Through customized solutions, your business will get adequate coverage without unnecessary costs. We’ll keep premiums cost-effective.
Our Testimonials
Hear from our clients
“We recently changed our business insurance after over 20 years, and we couldn't be happier. We didn't realize how poor the service was, how unresponsive, and slow the service was of our previous carrier. Dax and his team have gone above and beyond to answer every question our business had, to ensure that we had the coverage we needed, and fully understood everything we were getting. Not only did we save money, but we have saved a lot of time with the quick responsiveness of this team. They are exceptional. Would Highly recommend, and provide references."
Laura Harrison
May 2021
"I love working with the ERM crew! They are always super inquisitive and willing to learn/ask questions to provide their clients with the best possible insurance solution. I would definitely recommend them to anyone looking for advice on their current policies and coverage."
Nicole Limpert
May 2021
“Elemental Risk Management has been our insurance agent for 2 years now. They are consistently shopping for us to have the very best quality of coverage, as well as the best rates available. They saved our company over $20,000.00 in premiums our first year doing business with them. They are also quick to respond to any need (COI's, accident reporting, etc.). I recommend the team at ERM very highly!
Ramona Mills
June 2021